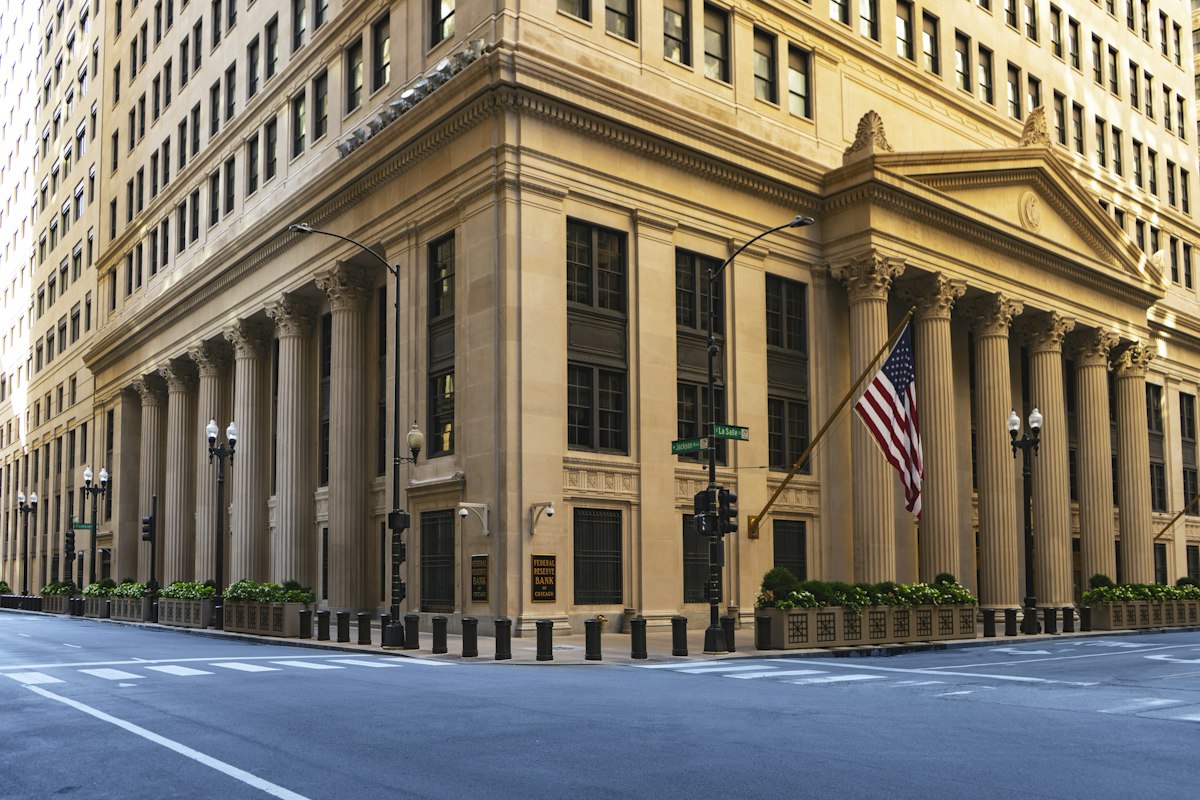
Fed independence emerged as the surprise survivor on Monday, even as the Supreme Court spent the day demolishing one of the load-bearing walls of the modern administrative state. In Trump v. Slaughter, a 6-3 majority overruled Humphrey's Executor, the 1935 precedent that for ninety-one years had let Congress shield the leaders of independent agencies from being fired at the president's whim. The decision hands the White House sweeping authority over bodies such as the Federal Trade Commission, whose commissioner Rebecca Slaughter can now be removed without cause. Yet in a companion case, the Court held that Fed independence remains intact, and that carve-out is the detail markets seized on.
By Blumefield | July 1, 2026
A Ruling That Cut Two Ways
Chief Justice John Roberts wrote for the majority with a bluntness that left little ambiguity about the direction of travel. "If anything more is left of Humphrey's, we overrule it," he declared. Fed independence was preserved not because the old logic survived, but because Roberts treated the central bank as a constitutional species of its own, a body he described as historically unique and distinguishable from ordinary regulators like the FTC or the Equal Employment Opportunity Commission.
The split verdict produced a strange spectacle. The same Court that expanded presidential power to its widest point in a generation also drew a bright line around the one institution investors care about most. For anyone tracking Fed independence as a market variable rather than a legal abstraction, the message was that the guardrail bent almost everywhere except where the money is.
Why the Fed Got Its Own Rule
The reasoning that spared the central bank arrived through an unusual coalition. Roberts and Justice Brett Kavanaugh joined the Court's three liberal members to form a 5-4 majority in the Fed case, a lineup that would have seemed improbable in almost any other dispute this term. Their shared premise was that the Federal Reserve occupies a distinct historical and structural position, rooted in a lineage of quasi-independent financial bodies that predates the New Deal experiment the Court had just dismantled.
That historical framing matters because it gives Fed independence a foundation that does not depend on Humphrey's Executor at all. Rather than resting the central bank's protection on a precedent the majority clearly distrusts, Roberts anchored it in the specific character of monetary policy and the long tradition of insulating it from short-term political pressure. The seven members of the Fed's Board of Governors, under this ruling, cannot be dismissed without a genuine cause, and the bar for what counts as cause is high.
The practical stakes are enormous. A president who could fire Fed governors at will could, in theory, install loyalists willing to slash rates on command, monetize deficits, or bend policy to an election calendar. Investors have long priced Fed independence as a quiet assumption behind the value of Treasury bonds and the credibility of the dollar. By reaffirming that assumption, even through a fractured majority, the Court removed a tail risk that had been building for more than a year. The relevant government record is public in the Court's own opinion in the Cook matter, and in the composition of the Federal Reserve Board of Governors.
The Market Read the Verdict Instantly
Wall Street did not wait for the legal commentary to settle. The Dow Jones Industrial Average closed above 52,000 for the first time in its history, finishing at 52,182.74 after adding 306.63 points, a gain of 0.59 percent. The S&P 500 rose 1.18 percent to 7,440.43, while the tech-heavy Nasdaq Composite surged 2.07 percent to 25,820.14, recovering ground it had shed the previous week during a bout of artificial-intelligence valuation anxiety.
Three catalysts converged on the same session. The ruling that protected Fed independence removed a source of macro uncertainty. Alphabet made its debut as a member of the Dow, replacing Verizon after twenty-two years and climbing more than 4 percent on its first day in the index. And a further de-escalation in the Middle East pushed crude oil lower, easing one of the year's most persistent inflation threats. For a market that had spent weeks fretting over whether the rally had run too far, the combination read as permission to buy.
It would be too neat to credit the entire record close to a single opinion. Yet the timing was not coincidence. A politicized central bank is the kind of risk that does not show up in daily price action until it suddenly dominates it, and traders know the difference between a Fed setting policy on its own judgment and one taking orders from the Oval Office. Preserving Fed independence, however narrowly, kept that scenario off the table for now.
What "For Cause" Actually Means Now
The most immediate human consequence of the decision landed on Governor Lisa Cook, whom the administration had moved to remove over contested allegations of mortgage fraud. The Court ruled 5-4 that Cook can keep her seat while the underlying litigation plays out in the lower courts, a procedural win that doubles as a substantive statement about how hard it should be to oust a sitting governor.
Crucially, the majority narrowed the definition of what would justify removal. The White House had argued that it alone could define "cause" and that its judgment could not be second-guessed by any court. The justices rejected that expansive reading, indicating instead that cause likely means serious misconduct unrelated to a governor's performance of monetary duties. In other words, disagreement over interest rates is not a firing offense, and a president cannot manufacture cause simply by asserting it. That standard is the operational core of Fed independence, and it now has fresh judicial backing.
The contrast with the FTC could not be sharper. Rebecca Slaughter enjoys no such protection, and the same is true for the leadership of most other agencies Congress once tried to insulate. A single Monday redrew the map of the federal government, concentrating power in the presidency almost everywhere while fencing off the central bank as a constitutional exception.
A Reprieve With an Expiration Date
The celebration on trading floors should be read with a measure of caution. The Court preserved Fed independence, but it did so through a 5-4 margin that depended on Roberts and Kavanaugh, and it left the Cook case unresolved on the merits. Litigation continues in the lower courts, and a future majority could revisit the boundaries of what counts as cause. Justice Sonia Sotomayor, in a pointed dissent to the broader ruling, warned that the Court had handed the presidency something close to the powers of a king. Her argument was aimed at the agencies that lost their shield, but the logic she fears could, in another case, press against the central bank too.
There is also the matter of vacancies. A president who cannot fire governors can still appoint them as terms expire, gradually reshaping the Board through the ordinary machinery of nominations. Fed independence protects the institution from a sudden purge, not from patient turnover. The market's relief reflects the removal of the dramatic threat, not the elimination of political influence over monetary policy, which remains real and constant.
For investors, the takeaway is that a structural risk has been downgraded rather than erased. The rally that carried the Dow past 52,000 was a rational response to a genuinely important ruling, and Fed independence is more secure today than it looked a week ago. But the ruling rested on a fragile coalition and an unfinished case, and the same Court that spared the central bank showed exactly how willing it is to tear down precedents it no longer respects. Readers following this story can track the fallout through Blumefield and our continuing coverage of the Federal Reserve's shifting balance of power. The wall held this time. Nobody should assume it is load-bearing forever.