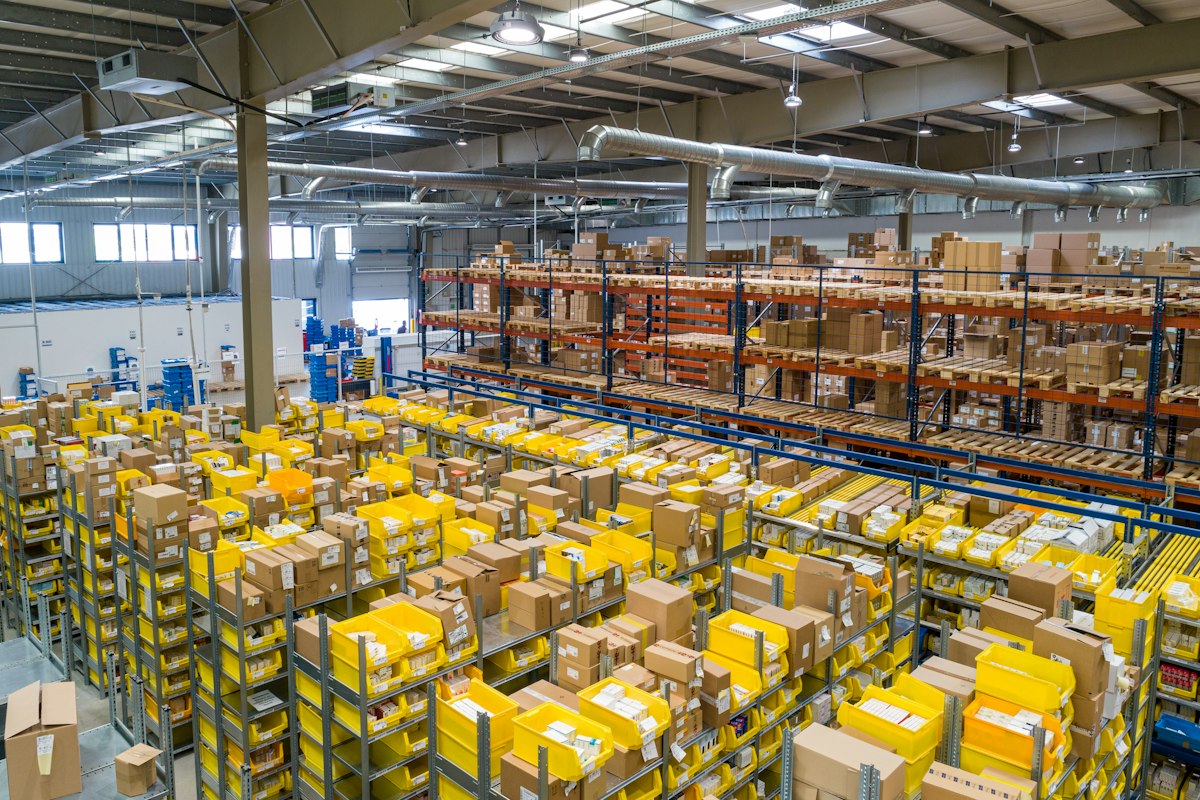
The Prologis Segro takeover has reached the week that will decide it, and the stakes stretch far beyond two property companies.
By Blumefield | July 13, 2026
A Deadline That Concentrates Minds
Every hostile approach eventually meets a clock, and the Prologis Segro takeover now has one that cannot be ignored. Under Rule 2.6(a) of the United Kingdom City Code on Takeovers and Mergers, Prologis must decide by 5pm London time on July 22 whether to table a firm offer for Segro or step away for at least six months. That single date has turned a slow corporate courtship into a countdown, and it explains why both sides have spent the past fortnight briefing investors rather than each other.
Prologis, the largest owner of warehouses on the planet, went public with its interest on June 24 after Segro's board rejected a private approach the day before. The all-share proposal values the British landlord at roughly £12.6 billion, or about $16.9 billion, and offers Segro holders 0.084 new Prologis shares for each share they own. At announcement that implied 925 pence a share, a premium of around 25 percent to where Segro had been trading. On paper it looks generous. Segro's directors call it opportunistic.
The disagreement at the heart of the Prologis Segro takeover is not really about a number. It is about timing, and about what a warehouse company is worth in an age when the most valuable thing a landlord can own is a plot of land with power running to it.
Why Warehouses Became A Power Business
For two decades the industrial property story was about e-commerce. Retailers needed sheds near cities to move parcels quickly, and firms like Prologis and Segro built them by the million square foot. That trade still runs, but a second, hungrier tenant has arrived. Data centres now compete for the same scarce ingredients as logistics warehouses, namely large flat sites, grid connections and, above all, electricity.
Segro sits on the richest seam of that opportunity in Europe. Its estate on the Slough Trading Estate west of London is the continent's largest data centre cluster, and the company has roughly 500 megawatts in operation or development around that site alone. Management has pointed to more than 2.5 gigawatts of further potential capacity across the United Kingdom and continental Europe, with around 1.1 gigawatts it hopes to pre-let by the end of 2028. In an environment where new grid connections can take years to secure, that pipeline is close to irreplaceable.
This is the quiet logic driving the Prologis Segro takeover. Prologis has told Segro shareholders they would gain from a larger, better capitalised data centre platform able to develop both companies' pipelines faster than either could alone. Segro has secured power. Prologis has the balance sheet and the American hyperscaler relationships to fill it. On that reading the deal is less a property merger than a bet on where the next decade of computing gets built.
Segro Says No, For Now
Segro's board has been blunt. It rejected the approach unanimously on June 23 and has repeated since that the offer falls a long way short of its own view of value. The argument against the Prologis Segro takeover rests on the idea that Prologis is trying to buy the data centre pipeline before the market has fully priced it, locking in the upside for its own shareholders rather than Segro's.
There is force in that. Segro's overall portfolio is valued at around £22 billion, and the company reported £53 million of new headline rent signed in the first half of 2026, up sharply from £31 million a year earlier. A board can reasonably argue that a business signing leases at that pace, with gigawatts of optionality behind it, should not be sold at a 25 percent premium struck against a depressed share price.
Yet rejection is not the same as immunity. Because the bid is all-share, Segro's own investors get a say in practice long before any formal meeting. Several large holders have already urged Prologis to improve the terms rather than dismissing the idea outright, which tells its own story. The board can hold the line on price. It cannot easily hold the line on the principle that the two businesses should never combine.
The Numbers Behind The Standoff
Strip away the rhetoric and the Prologis Segro takeover comes down to a few figures. The 0.084 exchange ratio fixes Segro holders' fortunes to Prologis stock, so the headline 925 pence moves with the American company's share price and with sterling. That is a feature for Prologis, which conserves cash, and a risk for Segro holders, who would be swapping a focused European landlord for a slice of a sprawling global one.
Then there is the premium. Twenty-five percent sounds healthy until you consider that industrial property shares across Europe have traded below the value of the bricks they own for much of the past two years. A premium to a discounted price can still leave sellers short of what the assets are worth if held and developed. That gap, between market price and development value, is exactly the space Prologis is trying to arbitrage, and exactly the space Segro's board is trying to defend.
Scale is the third number. A combined group would be the dominant industrial and data centre landlord in Europe by a wide margin, which raises the prospect of competition scrutiny and gives regulators in London and Brussels a reason to look closely. For a business model that depends on controlling scarce sites near power and population, market power is the point and also the problem.
What Happens After July 22
The paths out of the Prologis Segro takeover reduce to three. Prologis can lift its offer, most plausibly by adding a cash component or nudging the ratio, and dare the Segro board to reject an improved deal in front of its own shareholders. It can walk away and return after the six month restriction lapses, betting that a weaker Segro share price makes the maths easier later. Or it can hold firm and let the deadline pass, wagering that investor pressure does the persuading.
Whatever Prologis chooses, the episode has already made a wider point that reaches well beyond two property companies. The scramble for warehouse groups is now a scramble for the physical foundations of artificial intelligence. Land, power and permits have become the choke points of the computing boom, and the firms that assembled them for parcels and pallets suddenly find themselves holding the deeds to the data economy. The Prologis Segro takeover is the first big test of what that scarcity is worth. For more coverage of the infrastructure behind the AI build out, follow Blumefield.
Readers can track the formal timetable through the UK Takeover Panel and read the bidder's own case in the Prologis investor announcement. Details of the target's power pipeline sit on Segro's data centre pages.